Drew Anger/Getty Images News
As I predicted in its earnings preview, Apple (NASDAQ:AAPL) delivered great results in fiscal Q2, against much tougher comps, which were better than Wall Street’s estimates. The iPhone was, in fact, the star of the show, as was the Mac. Concerns about sales in Greater China did not abate, and Apple managed to grow revenue in all of its top geographies, except for the smallest Asia Pacific East-China and East-Japan conglomerates.
The problem was not what Apple managed to do over the past three months, but rather what the company expects to face in the near future. The stock sold out during the earnings call, as the management team guided for substantial top-line challenges with its supply chain from component shortages and COVID-19 disruptions. Below are what I believe investors should stay away from on this wonderful earnings day.
Nothing Wrong in Fiscal Q2
Analysts were expecting fiscal Q2 revenue and EPS growth of 5% and 2%, respectively, while I thought 7% and 10% looked more realistic. The Cupertino company delivered an encouraging 9% growth in both the top and bottom lines, which, while aligned with my estimates, I still found impressive.
Considering all the recent challenges: inflation, supply chain problems, Russia’s sanctions, just a few hot topics, Apple and its management team should be commended for executing so well. In fact, this level of competency in running a business in nearly any macroeconomic environment helps me maintain confidence in AAPL, a valuable stock that I still think is worth owning.
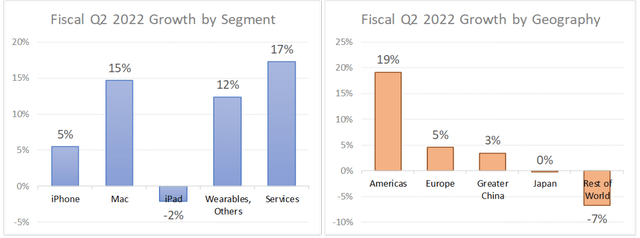
The chart below helps illustrate why Apple’s results were very strong across the board — keep in mind, the company’s overall revenue growth was 54% in the second quarter of last year. Some asterisks can be added here: (1) services growth slowed to mid-2020 levels, nearly 5 percentage points behind the previous 16-quarter average, and (2) supply chain constraints to the iPad outpaced other products. There was more damage in comparison and, perhaps, as I anticipated a few days ago, a lack of newness outside the iPad Air lineup.

Apple’s fiscal Q2 growth by business and by geographic segment (DM Martins Research)
Fiscal Q3 will be worse
All of the above helps justify the after-hours rally, as Apple stock climbed as much as 3% after rising nearly 5% during the regular trading session. That’s when CFO Luca Maestri gave the outlook for fiscal Q3 and shares fell: -4% to their lowest point, before recovering one to two percentage points by 6 p.m. EST.
Apple expects a substantial increase in Q3 revenue to $4 billion to $8 billion due to component shortages and COVID-powered plant closures in the Shanghai area. I was also a little disappointed to see gross margin guidance of 42% to 43% suggest YOY margin contraction for the first time since the last quarter of fiscal 2019. Meanwhile, the OPEX, directed at $12.8 billion (the midpoint of the range), remains rich enough. To suggest a notable loss of operating leverage.
The bottom line is that Apple’s fiscal Q3 P&L will likely be ugly compared to what investors have seen since the 2019 holiday quarter. Judging by the comments from the management team, demand doesn’t seem to be an issue, as the iPhone 13 and M1-equipped Mac devices are still successful. However, supply chain problems should be enough to drag down near-term results.
The good news that investors can stick to is that the worst may be over by the end of the quarter, according to CEO Tim Cook. Almost all of Apple’s final assembly facilities in China have already reopened, though not in time to prevent the loss of revenue in the current quarter. The chief executive also believes that some of the lost sales can be recovered in the future, although it is difficult to say exactly how much.
focus on long term
As I mentioned above, Apple continues to navigate choppy waters at least as well as any other tech company in the world. It would be a false optimism to think that the challenges would ease after the fiscal third quarter, but it is less to believe that the worst could be over in a matter of weeks or even a few months.
I think Apple is a good stock in my opinion, given the demand for the company’s products and the appreciation of the brand at historic highs. While valuations are certainly not in the gutter, potential investors can take solace in the current 12% decline from the recent peak, which still looks like a good opportunity to buy AAPL on the downside.